Comparison
What is in each edition
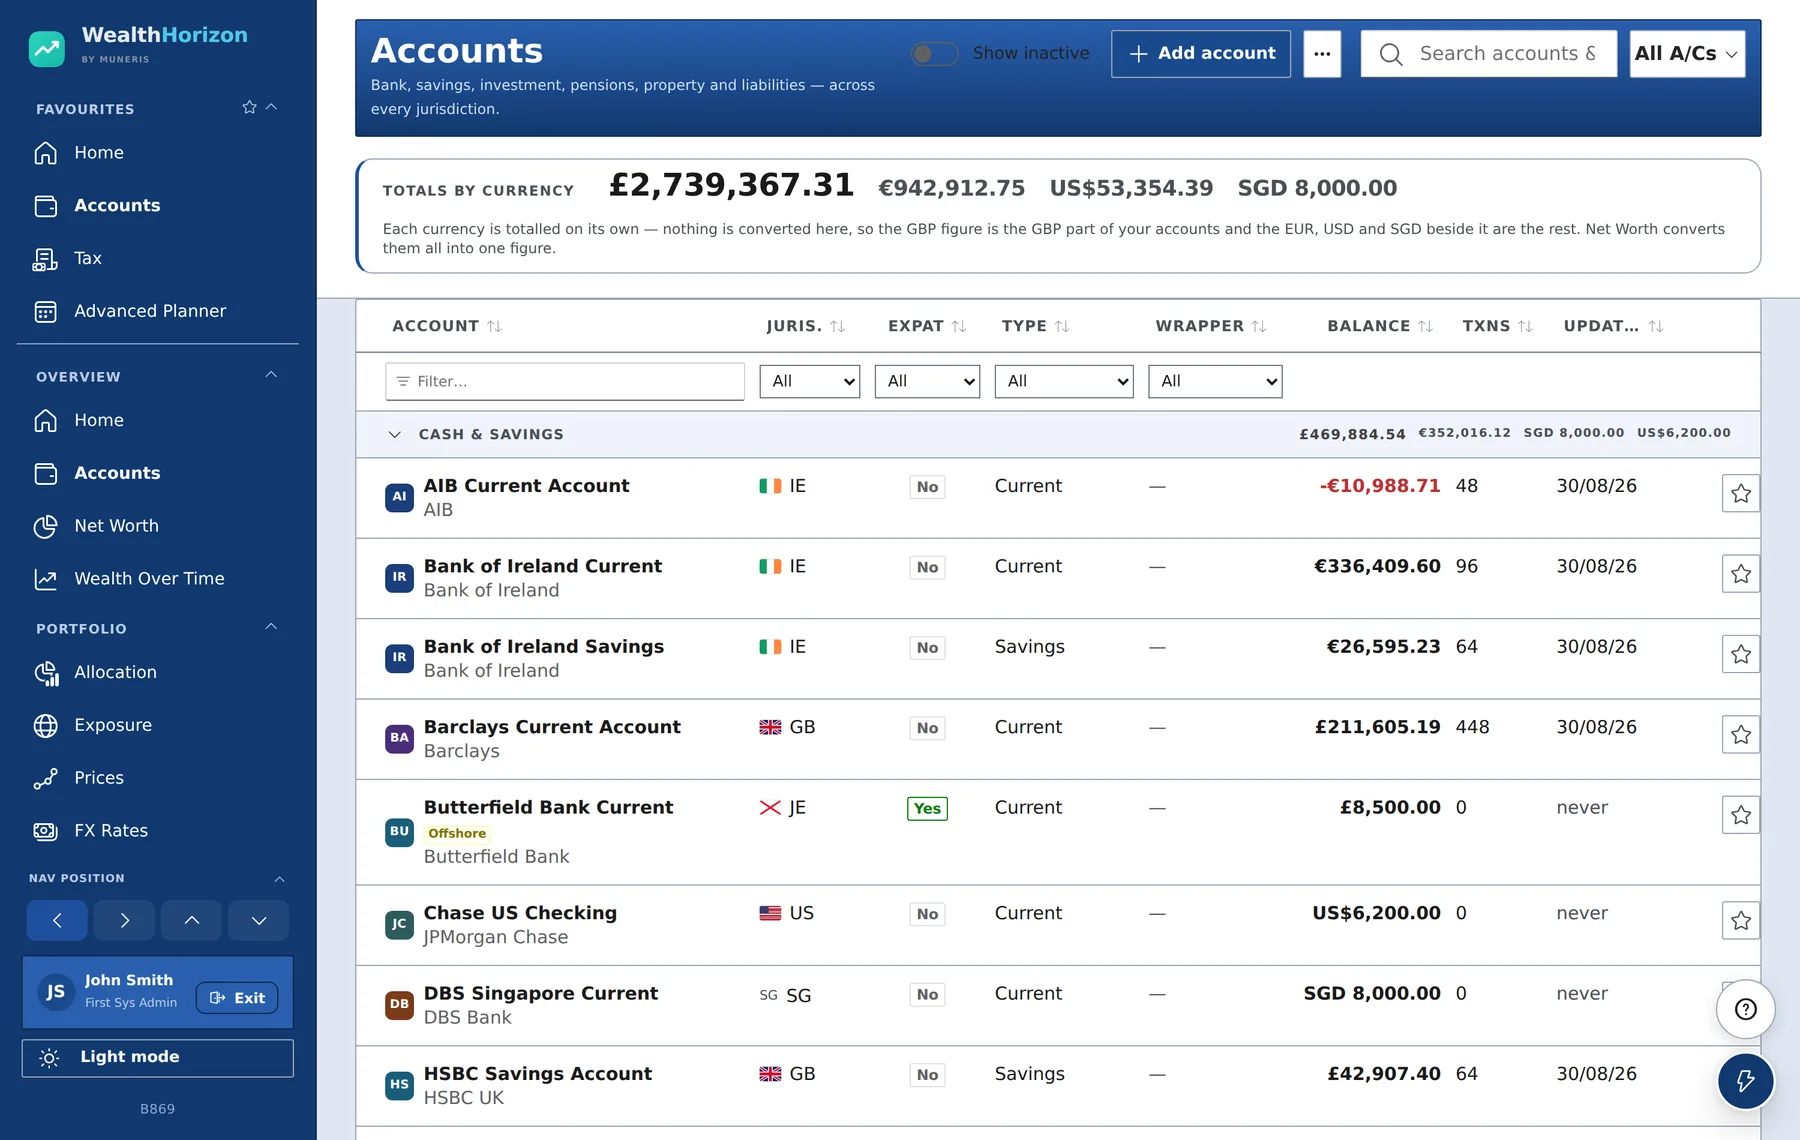
Free and Standard have exactly the same features. Three numbers separate them. Free stops at 30 accounts, 1,000 transactions and 5 MB. Standard stops at none of them. You install every edition on your own hardware, Free included. Pro adds everything to do with planning ahead, tax and forecasting. Advisory has all of Pro, plus the supervision and compliance tools described in The Advisory.
✓ included · Partial included with a stated limit · — not in this edition
| Feature | Free | Standard | Pro |
|---|---|---|---|
| Limits | |||
| Accounts | 30 | Unlimited | Unlimited |
| Transactions | 1,000 | Unlimited | Unlimited |
| Storage, including the files you attachYour records and any documents filed against an account, counted together. | 5 MB | Unlimited | Unlimited |
| Time limit or trial periodFree is not a trial. It does not expire. | None | None | None |
| Export your data at any time | ✓ | ✓ | ✓ |
| Accounts and the register | |||
| Full account taxonomyCurrent, savings, credit card, loan, mortgage, investment, pension, property, vehicle, liability and more. | ✓ | ✓ | ✓ |
| Per-account country, currency and tax wrapperISA, SIPP, GIA, QROPS, bonds, pensions; offshore flag. | ✓ | ✓ | ✓ |
| Transaction register with a running balance | ✓ | ✓ | ✓ |
| Split transactions | ✓ | ✓ | ✓ |
| Matched transfers between your own accountsDouble-sided and linked, including across currencies. | ✓ | ✓ | ✓ |
| Payees, with logos and a website guessed from the narrative | ✓ | ✓ | ✓ |
| Categories, including your own | ✓ | ✓ | ✓ |
Arithmetic typed into an amount box120+45.50+18, 240/3. | ✓ | ✓ | ✓ |
| Bulk edit and bulk delete | ✓ | ✓ | ✓ |
| Credit-card headroom, statement cycle and payment day | ✓ | ✓ | ✓ |
| Loans and mortgages with an interest rate and schedule | ✓ | ✓ | ✓ |
| Payslip breakdown — gross to net, reconciled to the bank | ✓ | ✓ | ✓ |
| The institution’s mark beside each accountWorked out from the account’s own name, so “Scottish Widows Personal Pension” finds Scottish Widows. Where it cannot tell, you get coloured initials. | ✓ | ✓ | ✓ |
| Which accounts you hold at each institution | ✓ | ✓ | ✓ |
| Money coming in and going out | |||
| Repeating income and payments, weekly to yearly | ✓ | ✓ | ✓ |
| The month of bills laid out as a calendar | ✓ | ✓ | ✓ |
| Estimated amounts, and a per-occurrence overrideSkip this month, change this month’s amount, move the date. | ✓ | ✓ | ✓ |
| Turn a register entry into a repeating item | ✓ | ✓ | ✓ |
| Renewals — insurance, subscriptions, fixed-rate terms | ✓ | ✓ | ✓ |
| The policy behind the renewal dateWho it is with, the policy number, the cover and its level, what it cost, and the numbers to ring. The reminder email carries them, so you can act on it without opening the app. | ✓ | ✓ | ✓ |
| Policy details read out of the insurer’s letterPaste the confirmation email in and it fills in the number, cover, dates and phone numbers. Anything it cannot find it leaves alone rather than guessing. | ✓ | ✓ | ✓ |
| Twelve-month cash-flow forecast | — | — | ✓ |
| Months of cover, on the home pageCash and savings divided by a month’s outgoings, with both figures written underneath. Below three months it says so. | — | — | ✓ |
| Month-end funding planThe picture of the month per account, the transfer worksheet, the reason each source was chosen. | — | — | ✓ |
| Bank instruction list, grouped by the login you use | — | — | ✓ |
| Saved transfer lists and a movement journal | — | — | ✓ |
| Minimum planned balance and earmarked money | — | — | ✓ |
| Monthly pack — one printable run of where you stand | — | — | ✓ |
| Investments and portfolio | |||
| Holdings, quantities and prices in the quoted currency | ✓ | ✓ | ✓ |
| Lot tracking on every purchase and disposal | ✓ | ✓ | ✓ |
| An investment account’s own cash side | ✓ | ✓ | ✓ |
| Share splits and consolidations | ✓ | ✓ | ✓ |
| Price history, a chart over time and a benchmark to compare against | ✓ | ✓ | ✓ |
| Open a holding from the table, with its price history beside anotherHow many you hold, the price and when it was taken, the market value, what it cost, and the gain. | ✓ | ✓ | ✓ |
| Say where a purchase cost was never recordedRather than showing nought and treating the whole value as profit. | ✓ | ✓ | ✓ |
| Manual price entry and price import | ✓ | ✓ | ✓ |
| Automatic price refresh from a market-data provider | ✓ | ✓ | ✓ |
| Valuations you enter for accounts that cannot price themselvesA workplace pension holds no instrument with a market price; a statement is the only source there is. | ✓ | ✓ | ✓ |
| Asset allocation by class, geography and sector | ✓ | ✓ | ✓ |
| Currency exposure | ✓ | ✓ | ✓ |
| Rebalancing against a target allocation | — | — | ✓ |
| Dividend tracker with withholding tax | — | — | ✓ |
| CFD and spread-betting accounts | ✓ | ✓ | ✓ |
| Share price forecast grid, per instrument and per date | — | — | ✓ |
| Net worth and currency | |||
| One net worth figure, with the sum shown line by line | ✓ | ✓ | ✓ |
| Snapshots and a net-worth chart over time | ✓ | ✓ | ✓ |
| What a point on the chart is made of, account by accountEach line of an imported tracker beside WealthHorizon’s own figure for the same date, and the difference. | ✓ | ✓ | ✓ |
| Reconcile an imported tracker, and say whether the spreadsheet can stopIt values every imported month the way it values one of its own, then tells you per column whether it matches, drifts or never matched, and the first month they disagreed. | ✓ | ✓ | ✓ |
| Fees in pounds, and what they cost over twenty yearsAgainst 0.3% on the same money. Accounts where you have not entered a fee are listed separately, so an empty box is not counted as nothing. | ✓ | ✓ | ✓ |
| How much is not in your base currency, and what a 10% move would do | ✓ | ✓ | ✓ |
| Any number of currencies, in one household | ✓ | ✓ | ✓ |
| Historic exchange rate held per transactionNative amount, base amount, rate, date and source, on every entry. | ✓ | ✓ | ✓ |
| Exchange rates fetched daily, without anyone opening the page | ✓ | ✓ | ✓ |
| Multiple jurisdictions in one picture | ✓ | ✓ | ✓ |
| Bringing data in and taking it out | |||
Import a Microsoft Money file.mny, .mdb/.accdb, and Money’s own export workbook. | ✓ | ✓ | ✓ |
| Import QIF and OFX | ✓ | ✓ | ✓ |
| Import any CSV or spreadsheet, with the columns mapped by you | ✓ | ✓ | ✓ |
| Broker and bank formats recognised automaticallyTrading 212, Saxo, Barclays and others. | ✓ | ✓ | ✓ |
| Preview and balance reconciliation before anything is saved | ✓ | ✓ | ✓ |
| Duplicate detection across the whole household | ✓ | ✓ | ✓ |
| Saved import profiles for a file you get every month | ✓ | ✓ | ✓ |
| Export to CSV, Excel, QIF and OFX | ✓ | ✓ | ✓ |
| Open Banking connection to a bankOptional, and never required for the product to work. | — | — | ✓ |
| Read-only broker connectionTrading 212. The trading endpoints are deliberately not reachable. | — | — | ✓ |
| Reports | |||
| Report gallery under Microsoft Money’s own headings | ✓ | ✓ | ✓ |
| Spending by category and by payee | ✓ | ✓ | ✓ |
| Period-against-period comparison reports | ✓ | ✓ | ✓ |
| Transactions by category, by payee, and per account | ✓ | ✓ | ✓ |
| Account balances with detail | ✓ | ✓ | ✓ |
| Saved reports you can return to | ✓ | ✓ | ✓ |
| Wealth report, printable or saved as a PDF | ✓ | ✓ | ✓ |
| Planning ahead | |||
| Savings goals with a progress estimate | ✓ | ✓ | ✓ |
| Savings estimator — what it would take to reach a figure | ✓ | ✓ | ✓ |
| Guided planning wizard, with the questions that apply to you | — | — | ✓ |
| Advanced Planner — year-by-year projection with your own assumptions | — | — | ✓ |
| Need-driven drawdown from a stated target spendGuaranteed income first, taxed; the shortfall drawn from pots in the order you set. | — | — | ✓ |
| Cautious, expected and optimistic outlooks | — | — | ✓ |
| Monte Carlo simulation | — | — | ✓ |
| What-if scenarios that are not saved to the plan | — | — | ✓ |
| Pensions, income streams, inflation and retirement spending | — | — | ✓ |
| FIRE mode — FIRE number, savings rate, Coast, Barista, bridge planner | — | — | ✓ |
| Roadmap — goals, plan and actual wealth on one timeline | — | — | ✓ |
| Multiple plans, exported and imported as files | — | — | ✓ |
| Every assumption listed, with where its value came fromAn account, a tax table, something you typed, or a default nobody has touched. | — | — | ✓ |
| One-click questions worked out from your own figuresMarkets return 2% less. Retire two years later or earlier. Take the tax-free cash at once. Move to Jersey. Give £10,000 a year. Fill the basic-rate band. | — | — | ✓ |
| A scenario can change any assumption, including where you live for tax | — | — | ✓ |
| Scenarios compared on lifetime tax, first shortfall and years below minimum cashWith the list of exactly which assumptions differ. | — | — | ✓ |
| Monte Carlo run on the same engine as the forecastSo the middle of the range is the line you were shown. | — | — | ✓ |
| Baselines — the plan frozen, then checked against what happenedYear by year and pot by pot, read from your own end-of-year snapshots. | — | — | ✓ |
| A prompt each January to look at the plan againWhich tax tables it is using, which assumptions are still at their defaults, whether the baseline is stale. | — | — | ✓ |
| A plan report, as a workbook or a page to print | — | — | ✓ |
| The whole plan exported and imported as one filePeople, pensions and income streams included. Import what you exported and the forecast comes back the same. | — | — | ✓ |
| A settings workbook to fill in and read back | — | — | ✓ |
| Pension calculator — two questions, answered from the pensions you holdThe age you want to stop and how much tax-free cash. It draws the answer year by year and lists every pot behind it. | — | — | ✓ |
| Tax-free cash held to each jurisdiction’s rulesA share of the pot and a lifetime ceiling on top of it — £268,275 in the UK, €200,000 in Ireland, 30% of an approved scheme in Jersey. | — | — | ✓ |
| A pension taken as a series of lump sumsRather than tax-free cash once and drawdown after it. Both routes spend the same ceiling. | — | — | ✓ |
| The money purchase annual allowance, applied once taxed money comes outFrom the year after the first taxed withdrawal, with contributions scaled to fit and the shortfall stated. | — | — | ✓ |
| The forecast taxed with the real bands, every yearNot one flat rate. The same arithmetic the Tax page runs, for the year and the country, with a withdrawal grossed up to leave you what you need after tax. | — | — | ✓ |
| Tax years on the forecast, and thresholds that thawEach row carries its tax year as well as its calendar year. Thresholds hold their published value through the freeze, then rise with your inflation figure. | — | — | ✓ |
| Capital gains tax on what you sell to live onThe gain share from each account’s own cost base where the records exist, with the annual exempt amount and the rates for your band. | — | — | ✓ |
| Dividend tax by band, outside an ISA | — | — | ✓ |
| A couple taxed as two peopleEvery pension, income stream and pot names whose it is. Each gets their own allowance, bands, capital gains exemption and dividend allowance. | — | — | ✓ |
| Draw pension up to the top of the basic-rate bandOptional. Anything spare goes to cash. | — | — | ✓ |
| A minimum cash balance the forecast will not go below | — | — | ✓ |
| Growth set per pot, or taken from your price forecastsAn account whose holdings have price forecasts grows at the rate those imply, until the forecasts run out. | — | — | ✓ |
| Tax checks — a row per check, a column per yearUnused basic-rate band, income in the 60% taper zone, tax-free cash still to take, spare ISA allowance, an unused capital gains exemption, cash below your minimum, pension drawn at the higher rate. | — | — | ✓ |
| Tax | |||
| Tax calculator — income, gains and allowances | — | — | ✓ |
| Allowances used and remainingISA, pension, CGT and others, with days to 5 April. | — | — | ✓ |
| Capital gains — FIFO or the full UK matching rulesSame day, then the following 30 days, then the pool. | — | — | ✓ |
| CGT optimiser with loss-harvest opportunities | — | — | ✓ |
| Dividend tax and foreign withholding | — | — | ✓ |
| Up to three jurisdictions side by side | — | — | ✓ |
| Residency day counts and a travel timeline import | — | — | ✓ |
| Rate profiles and a rate history | — | — | ✓ |
| Irish deemed disposal — the eighth-year charge, lot by lotEvery open lot of an Irish fund with the date it falls due, the gain and the tax at the rate you set. | — | — | ✓ |
| Inheritance tax for every year of the forecastRules held as dated data rather than written into the code, so a change of rule is a change of row. | — | — | ✓ |
| Unused pensions in the estate from the year the rule startsApril 2027 in the UK. | — | — | ✓ |
| The residence nil-rate band, with its taperOnly where the home passes to direct descendants, capped at the home’s value, tapered by £1 for every £2 over the threshold. | — | — | ✓ |
| Nil-rate bands doubled where a late spouse’s transfers | — | — | ✓ |
| Business relief on holdings you flag as eligible | — | — | ✓ |
| A gift plan, with taper relief over seven yearsGifts take the nil-rate band first, oldest first. Tax above it tapers from the fourth year and falls on the people who received the gift, so it is reported separately. | — | — | ✓ |
| Income tax on an inherited pension, reported separatelyAfter a death at 75 or over. A different tax on different people, so it is not added into the inheritance tax. | — | — | ✓ |
| An unquoted company held as its own potNever drawn on, because there is no market to sell into on the day. It grows, and it counts in the estate. | — | — | ✓ |
| Says plainly where there is no inheritance taxJersey has none. You get the estate year by year and the reason nothing is taxed. | — | — | ✓ |
| Estate and inheritance tax | |||
| Estate valuation from your own accounts | — | — | ✓ |
| IHT liability with the nil-rate bands applied, shown line by line | — | — | ✓ |
| Residence nil-rate band | — | — | ✓ |
| Gift register against the seven-year rule | — | — | ✓ |
| Annual gift allowance tracking | — | — | ✓ |
| Estate planning strategies, quantified | — | — | ✓ |
| Household, documents and data | |||
| Documents filed against an account | ✓ | ✓ | ✓ |
| Household members, with per-account read, write or payment access | ✓ | ✓ | ✓ |
| Child accounts with a controlled access level | ✓ | ✓ | ✓ |
| Account Access — see who at a firm opened your account | ✓ | ✓ | ✓ |
| Share your plan with an adviser, and revoke it | — | — | ✓ |
| Open your whole planner to an adviser, read-onlyThe forecast, the tax, the inheritance tax and the scenarios. Every view is logged on your access record, and you can withdraw it at any point. | — | — | ✓ |
| A nominee who can see your accounts if you cannotThey can only look. They cannot change anything, cannot reach your backups or settings, and every visit is recorded for you. | ✓ | ✓ | ✓ |
| A waiting period you set, and a six-digit code, before a nominee gets inYou are emailed when access is asked for and can decline it or allow it early. Five wrong codes lock the code for half an hour. | ✓ | ✓ | ✓ |
| Readiness — what would be needed if something happened to youA nominee named and accepted, an expression of wish per pension, a will with its date and place, and a note for whoever picks it up. | ✓ | ✓ | ✓ |
| Manual backup and restore | ✓ | ✓ | ✓ |
| Scheduled backups with a retention count | ✓ | ✓ | ✓ |
| Backups encrypted with a passphrase you setAES-256-GCM, key derived with PBKDF2-SHA256 over 100,000 iterations. | ✓ | ✓ | ✓ |
| Data health — stale prices, missing rates, gaps | ✓ | ✓ | ✓ |
| Custom alerts on price and net-worth thresholds | — | — | ✓ |
| An alert when money appears that no total countsChecked every four hours. You are told once about each thing, not every week until you fix it. | — | — | ✓ |
| Accounts, access and platform | |||
| Runs in a browser on phone, tablet and desktop | ✓ | ✓ | ✓ |
| Two-factor authentication | ✓ | ✓ | ✓ |
| Dark mode, and a navigation rail you can move | ✓ | ✓ | ✓ |
| In-app manual and page-by-page help | ✓ | ✓ | ✓ |
| A Microsoft Money 2005 skin, beside light and darkThe navy rail, the blue banner, squared corners and Tahoma. The charts change colour with it. Nothing moves. | ✓ | ✓ | ✓ |
| Read your accounts with no connectionWhat you have looked at is kept on the device. A line across the top says what you are seeing and when it was saved. Signing out clears it all. | ✓ | ✓ | ✓ |
| Changes made offline are queued and sent when you are backIn the order you made them. It does not re-work your totals on the device, because that figure could be wrong and would still look right. | ✓ | ✓ | ✓ |
| Two devices cannot quietly overwrite one anotherIf another device got there first, the save is refused. Your typing stays on screen and the newer version is shown next to it. | ✓ | ✓ | ✓ |
| Sign-in attempts are rate limitedTen per account in fifteen minutes. A completed sign-in clears the count. | ✓ | ✓ | ✓ |
| Runs on your own hardware or cloudA database, an API and the web app. A laptop, a network drive, a server, or any cloud you already use. Every edition installs the same way, Free included. | ✓ | ✓ | ✓ |
| Works with no internet connectionMarket data, Open Banking and email are optional. Set up none of them and it still works. | ✓ | ✓ | ✓ |
About the storage limit. It counts your records and any documents you file against an account, added together. If you do not attach documents you will hit the transaction limit first. If you do, you will hit the storage limit first, because a few scanned statements take up more room than a year of entries. Free is held to 5 MB wherever you install it, because the limit belongs to the edition rather than the machine. Standard, Pro and Advisory have no limit but the disk you give them. WealthHorizon tells you which limit you are getting close to, rather than refusing a save without saying why.
The Advisory edition has everything in the Pro column, for every client. It adds the supervision, Consumer Duty and record-keeping tools the firm needs. The Advisory describes it in full.
Coming from Microsoft Money
WealthHorizon compared with Microsoft Money
Microsoft stopped selling Money in 2009 and switched off its online services in 2011. The free “Sunset” build still runs on Windows, offline and unsupported. A lot of people are still using it, because it does the job and nothing quite like it has come along since.
The table below says what carries over and what does not. Where Money did something well, it says so. WealthHorizon was written to do the same job, not a different one under a similar name.
| Capability | Microsoft Money | WealthHorizon |
|---|---|---|
| The product itself | ||
| Still sold and supported | No. Withdrawn from sale in 2009; online services ended in 2011. The Sunset build is unsupported and receives no fixes. | Yes. In active development, with a versioned release on every change. |
| Where it runs | A Windows desktop application, installed on one machine. | A browser. The same account on a phone, a tablet and a desktop, with layouts written for each. |
| Looks like Money | The navy rail, the blue banner across the top, squared corners and Tahoma. | Yes, if you want it. Money 2005 is a third choice beside light and dark. Same rail, same banner, same corners, same typeface, and the charts turn Money’s blues, reds and greens. Nothing moves. The pages, the figures and the menus stay where they are, and the type stays at a size you can read. |
| Where the data lives | A single .mny file on that machine. |
A PostgreSQL database on your own hardware. It exports in four open formats. |
| Works with no internet connection | Yes — the Sunset build has no online services at all. | Yes. Market data, Open Banking and email are optional; with none configured the product still works. |
| Reading it away from the desk | Nothing to read. The file is on the machine you left at home. | Accounts, balances, net worth and the last prices are kept on the device as you look at them. On a train the app opens and shows what it last saw, with a line across the top saying when that was. Changes you make with no signal are held and sent in order when the connection comes back. |
| More than one person | One file, one user at a time. | A household, with per-account read, write or payment access, and a controlled level for children. |
| The register — what Money was best at | ||
| Running balance after every row | Yes. The reason people reconcile in Money. | Yes — counted from the opening balance in date order, and correct on every page. Sort by something other than date and it greys out, because the figure only means anything in date order. |
| Arithmetic in the amount box | Yes. The most-missed thing about that register. | Yes, in every money field — 120+45.50+18, 240/3, -10+(2*8). |
| Splits | Yes. | Yes, including on imported rows and payslips. |
| Matched transfers between your own accounts | Yes, in one currency. | Yes, and across currencies — you enter the exact amount that arrived. |
| Bills and deposits as a calendar | Yes. | Yes, with estimated amounts, and a per-occurrence override for the month that is different. |
| Payees and categories | Yes. | Yes, with a logo beside each payee and a website worked out from the bank narrative. |
| Investments | ||
| Holdings and an investment account’s own cash | Yes. | Yes, with one rule for what an account is worth, so no two screens can disagree. |
| Automatic price updates | No longer. The quote service was part of the online services that ended in 2011. | Yes, with a daily price kept per instrument, so a year of holding something is a year of closes you can chart. |
| Lot tracking for capital gains | Partial. Cost basis was recorded, but not the UK matching rules. | Yes — FIFO or the full UK rules: same day, then the following 30 days, then the pool. |
| Share splits and consolidations | Yes. | Yes. A split is recorded as something that happened, not as an edit to the numbers it produced, so the history can always be rebuilt. |
| Unlisted holdings and workplace pensions | Partial — a manually maintained value. | Yes — you enter a value from the provider’s statement, and the app knows where that sits against imported and priced figures. |
| Currency and jurisdiction | ||
| More than one currency | Partial — one rate per currency, held as a current value. | Yes — every transaction keeps its own native amount, base amount, rate, date and source, so your history does not move when today’s rate does. |
| More than one country | No. Money shipped as separate national editions. | Yes — per-account jurisdiction and tax wrapper, residency day counts, and up to three tax jurisdictions side by side. |
| Reports and analysis | ||
| Report gallery | Yes — spending, comparison, transaction and balance reports under familiar headings. | Yes, arranged under Money’s own headings, so the report you used is where you would expect to find it. |
| Asset allocation and currency exposure | Partial. | Yes — by asset class, geography, sector and currency, with a rebalancing view against a target. |
| Net worth over time | Yes. | Yes, and you can open the sum underneath: each account, its rate and what it came to. |
| Planning and tax | ||
| Long-term retirement projection | A lifetime planner with fixed assumptions. | Yes (Pro) — your own assumptions, three outlooks, Monte Carlo, need-driven drawdown from a stated target spend, and a withdrawal order you set. |
| Month-end funding plan | No. | Yes (Pro) — what each account faces this month, what to move from where, why, and the list grouped by the bank you log into. |
| Share price forecasting | No. | Yes (Pro) — a grid of instruments against dates, imported from and exported to the spreadsheet you already keep. |
| Inheritance tax | No. | Yes (Pro) — the bill with nil-rate bands applied, the seven-year gift register, and the options costed. |
| Capital gains tax | Cost basis only. | Yes (Pro) — UK matching rules, allowance and losses, plus an optimiser that finds harvesting opportunities. |
| Adviser and compliance tooling | No. | Yes (Advisory) — a full FCA Consumer Duty suite. See The Advisory. |
| Getting your history across | ||
| Reading a Money file | — | Yes — .mny, .mdb/.accdb, and Money’s
own export workbook. It shows you the balances it worked out so you can check them
before anything is saved. |
| QIF and OFX | Yes. | Yes, both in and out. |
| Getting your data back out | Limited — QIF export, and reports to a spreadsheet. | Yes — CSV, Excel, QIF and OFX per account, plus a full encrypted backup you hold. |
| Backups | Yes — a copy of the file. | Yes — scheduled, retained, and encrypted with a passphrase you set. |
What this page says about Microsoft Money describes the product as Microsoft last released it, and the Sunset build that is still available. Microsoft and Microsoft Money are trademarks of Microsoft Corporation. WealthHorizon is not affiliated with Microsoft or endorsed by them.